
This week, we analyse private equity fund Verdane’s growth investment in Xpansiv - and how the company may put that money to work. More on that below.
Asymmetrix is the source of truth for stakeholders in the Data & Analytics industry. Bankers, investors, equity research analysts and consultants rely on our data to stay informed on trends and transactions in the sector and to analyse Data & Analytics deals.
Feel free to reach out directly to h.crean@asymmetrixintelligence.com to learn more about a subscription or book a meeting via Calendly.
Asymmetrix’s Inaugural Summit
Asymmetrix will host its inaugural Data & Analytics summit on Tuesday 3 November in Central London. The full-day event will bring together a highly curated group of Data & Analytics company executives, investors and advisors for meaningful networking and insightful conversation. The 25% early-bird discount ends on 9 October, so act fast!
On the agenda: the MCP pricing debate, the impact of AI on data company valuations, what’s next in private markets data and more.
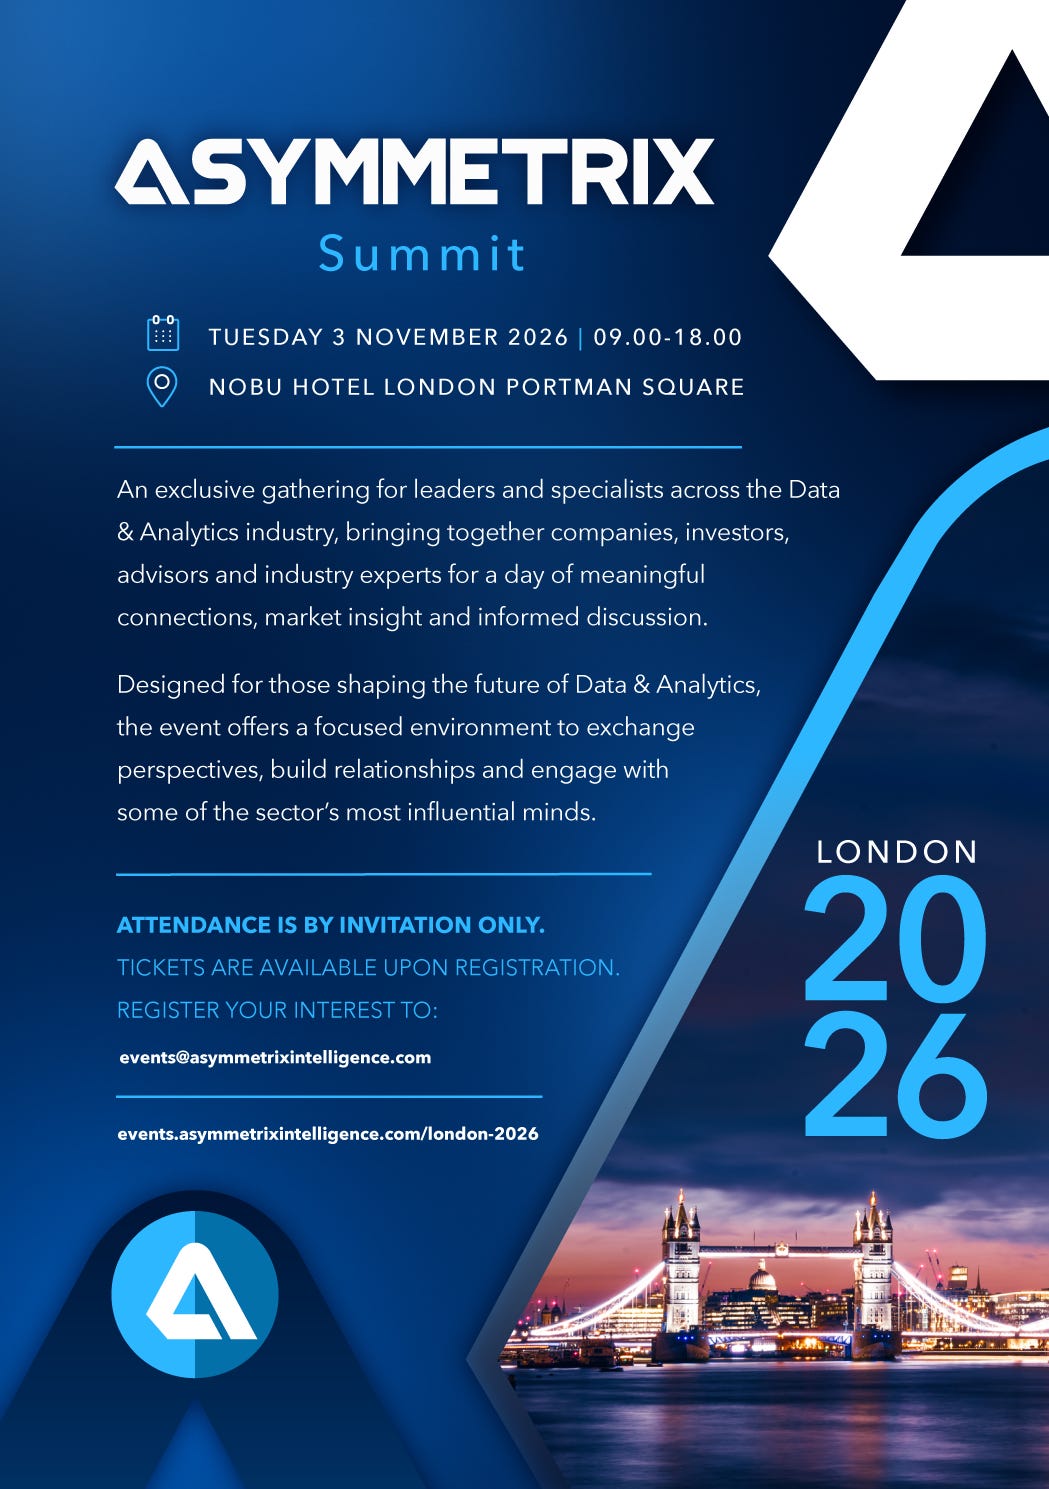
For more information, see our event website or email events@asymmetrixintelligence.com.
Can’t make the London event? Register your interest here for the Spring 2027 NYC event.
Take our AI Survey
Are you an investor or acquirer in the Data & Analytics industry? Take our three minute survey on the impact of AI on valuations in the sector and receive a free report analysing the survey’s results. You can take the survey here.
…and take our free data
Over 170 data executives, investors and advisors from Singapore to San Francisco have accessed our free MCP Tracker, which tracks Data & Analytics providers that have launched an MCP to date. Request access here.
Xpansiv by Name, Expansive by Strategy
On 22 September 2026, Xpansiv announced a growth capital raise led by Verdane, the European growth equity investor. Terms were not officially disclosed. The Australian Financial Review reported the raise at a little under $150m and stated that Xpansiv’s 2026 revenue is on track for roughly $150m, set against the $1.4bn post-money valuation at which Blackstone invested $400m in 2022 through a convertible note redeemable by 2028. The proceeds of the investment, according to the company, will fund acquisitions and continued expansion into new products, asset classes and geographies.
Verdane joins a blue-chip cap table: Blackstone, Bank of America, Goldman Sachs, Macquarie, Commonwealth Bank of Australia, Aware Super, Aramco Ventures and S&P Global Ventures are all prior backers of Xpansiv. Verdane’s investment offers the company acquisition capital and a foothold in European markets. “This partnership enables us to move faster on acquiring next-generation solutions to complement our internal innovation,” said Xpansiv chief executive John Melby.
This strategy was already in play the week the investment was announced. On 16 September, Xpansiv agreed to acquire Formbay, one of Australia’s largest compliance platforms for small-scale technology certificates (STCs), the local renewable energy certificate that underwrites rooftop solar and battery rollout.
The message is unambiguous: this is capital raised to be spent, and Formbay is just the start.
What Xpansiv does
Xpansiv converts fragmented, hard-to-verify claims about how electricity and carbon are produced into registry-issued, exchange-traded environmental instruments that corporates, utilities, traders and regulators use to prove and price provenance. Its rails span the full lifecycle: issuance and custody through a network of registries, trading through CBL (its spot marketplace for carbon and renewable energy certificates), brokerage through Evolution Markets, wholesale power and battery technology through APX, and market data across the whole.
The company’s scale is already considerable. Xpansiv’s registries support more than 320 gigawatts (GW) of renewable generation across more than 60 countries, process approximately one billion transactions a year, and represent, according to the company, roughly 4% of total global electricity generation and 7% of renewable generation. Around 28% of renewable energy certificates (RECs) issued globally in 2025 were managed on its network. In its April 2026 Price Reporting Agencies sector analysis (Part II), Asymmetrix profiled Xpansiv as operating one of the world’s largest integrated infrastructure platforms for environmental commodities, with CBL commanding roughly 25% of the voluntary carbon market (VCM) and registry connectivity across sixteen systems; the integration of Evident and the Formbay acquisition have extended that reach further.
The company’s moat is threefold:
Workflow moat – issuance and registry rails embedded in how various energy certificates are created, held and retired;
Authority moat – registries are the system of record, and CBL’s prices are market-clearing prints from a live order book rather than editorial assessments, a distinction Asymmetrix has argued is more defensible under regulatory scrutiny than survey methodologies;
Data moat – proprietary transaction data across the environmental complex. Breadth is not incidental to that moat; it is the moat. Each additional commodity, registry and geography makes the network the default place to prove provenance.
Asymmetrix’s estimates of Xpansiv’s financial and subscription metrics are available to subscribers.
Why Now?
Two forces meet in this financing round. One is demand for provenance. The binding change is regulatory and corporate: reporting and compliance obligations are widening, from mandatory Scope 3 disclosure to the certificate regimes that increasingly govern how large electricity buyers account for their consumption.
The largest new buyers are data centres, whose appetite for power, and for credible evidence of how that power is produced, is expanding faster than any other load. In an AI build-out, the electron and the certificate that describes it are becoming inseparable, and the infrastructure that issues and prices that certificate compounds in value.
The second force is capital and the repricing of data assets. The same institutional appetite for high-quality data assets that earned Kpler a $3.85bn valuation, and that is drawing private equity into environmental data (Permira into CDP, for one), is coming to a scaled platform with a genuine moat, notwithstanding its loss-making financial profile. The competitive strengths that matter here are structural rather than cyclical: a downturn would slow funding, but it would not affect Xpansiv’s unique positioning.
Strategy is Already in Motion
Xpansiv’s history reads as a single, consistent build: assemble the integrated rail across issuance, trading and data, then push it into new commodities and geographies.
Evident (November 2025) brought the International REC Standard (I-REC) registry and Evident’s provenance tooling, extending Xpansiv from a largely North American certificate footprint to a genuinely global one;
Formbay (September 2026) does the same for Australian compliance certificates.
Xpansiv has completed more than a dozen acquisitions since 2017; it has the integration muscle. What Verdane’s capital changes is the size and the cadence of what comes next.
Where Xpansiv Wins on Scale, and Where the Gaps Are
The 28%-of-RECs and 320-GW figures deserve reading with care, because they describe a specific universe. Xpansiv is, on Asymmetrix’s assessment, the largest integrated commercial environmental registry network in the world. Its true competitors on the registry rails are mostly not other companies but regional, utility or non-profit systems: in the United States, fragmented instruments such as WREGIS, M-RETS, PJM-GATS and NEPOOL-GIS; in carbon, the standards bodies Verra and Gold Standard. No single commercial operator matches Xpansiv’s breadth across commodities and countries.
But the same figures expose the clearest white space. Xpansiv’s REC share is a share of the global voluntary and I-REC universe. The European market runs on a different rail entirely: guarantees of origin (GoOs), issued by national bodies under the EU Renewable Energy Directive and coordinated through the Association of Issuing Bodies, form one of the largest pools of tradable electricity-attribute certificates in the world, and Xpansiv touches it through Evident’s I-REC footprint rather than owning the core European infrastructure.
Two gaps follow directly, and they may define the shopping list: geography – Europe, specifically the GoO complex and product – a governed benchmark and an integrity layer that its exchange-and-registry model does not itself provide. Verdane, European-based and fresh from acquiring bp Ventures’ energy technology portfolio, is a pointed choice of partner for exactly the first of these.
Who’s next? Asymmetrix names names
Asymmetrix’s database surfaces a field of targets that may be a strategic fit for Xpansiv on size, strategy and, most importantly, on the specific commodity and geographic gaps highlighted above.
European guarantees of origin and energy-transition pricing (fills the geographic gap), likely Xpansiv’s first stop. Veyt is the standout provider in this market: it prices GoOs, power purchase agreements (PPAs), RECs, carbon, renewable fuels and hydrogen across European and international markets. This is precisely the category Asymmetrix flagged in our analysis of PRAs as one where traditional agencies have limited specialist depth and regulatory relevance is rising. Montel Group would add real-time European power data, news and analytics at greater scale. Either would give Xpansiv European market intelligence to sit above European issuance, and a base from which to pursue the GoO rails themselves.
A benchmark and price-reporting layer (fills the product gap). CBL marketplace produces market-clearing prints, but not governed, editorially assessed benchmarks of the kind institutions settle contracts against. Quantum Commodity Intelligence, focused squarely on carbon, biofuels, ammonia and hydrogen, would convert Xpansiv from a venue into a benchmark authority. General Index, an algorithmic benchmark provider spanning carbon and energy, is another alternative, though likely too early stage to consider a sale. This is the same logic that took S&P Global from Platts into the reference price business, and that sits behind the S&P-Kaiko indices in crypto: whoever owns the benchmark owns the most defensible layer.
A carbon-integrity and ratings layer. The binding constraint on voluntary carbon is quality, not access. Sylvera Carbon Data, BeZero Carbon and Calyx Global (independent carbon-credit ratings), Renoster (measurement, reporting and verification, or MRV) and Abatable (procurement and market intelligence) would let Xpansiv wrap its listings in an integrity signal. The possible tension here is that an exchange that also rates the instruments it lists invites exactly the independence question that ratings exist to answer. The cleaner path is to buy analytics and MRV rather than an editorial ratings badge, or to hold any ratings asset at arm’s length.
Power and battery market analytics. If the deal narrative is electrons and data centre demand, forward power analytics is the most direct way to monetise it, and it dovetails with APX’s battery position. Ascend Analytics and Orennia both offer AI-driven power and battery energy storage system (BESS) analytics at bolt-on scale. LevelTen Energy, whose PPA marketplace and PPA Price Index already span the US and Europe, is the most strategically potent of the three, adding a clean energy transaction rail and European reach at once, though a recent ABB Ventures investment signals it will not be cheap or a near-term acquisition target.
Clean fuels, gas and specialty commodities (fills commodity gaps). ResourceWise brings low-carbon fuels and feedstock pricing - and is likely to become available in the near- to medium-term; Project Canary’s methane measurement and certified-gas credentials complement Xpansiv’s MiQ certified gas registry directly. In water, where Xpansiv already runs the H2OX marketplace, WestWater Research, which Asymmetrix earlier named as a builder of water rights pricing authority, and Global Water Intelligence would deepen a thin but strategically distinctive commodity. And in the carbon-removal (CDR) white space that Asymmetrix earlier identified as underserved, a registry such as Isometric is a build-or-buy question, though its recent $50m series A raise makes it a richly priced one.
Our Take
The strategic logic of this deal is sound, and the more consequential part of it is the acquisition mandate, not the product roadmap. Xpansiv is doing in environmental markets what the scaled incumbents did in financial data: consolidating fragmented infrastructure into a single set of rails, then defending it with breadth. The capital, the European partner and the same-week Formbay deal all point in the same direction.
Where we would place the highest conviction is Europe expansion and pricing data. The GoO (guarantees of origin) complex is the single largest geographic gap in an otherwise global network, and Verdane is the right partner to open those doors. A European energy transition data asset such as Veyt or Montel might be the logical first move. A benchmark franchise (Quantum Commodity Intelligence, General Index) is the highest-value structural addition.
What to Watch
Which geography moves first – given Verdane’s European base and its bp Ventures relationships, the European guarantee-of-origin complex may be the most likely early target; watch for a Nordic or UK energy-transition data acquisition.
Whether Xpansiv buys a benchmark provider – an acquisition of a price reporting agency in carbon, biofuels or hydrogen would be the clearest tell that it intends to own pricing data.
Whether it enters carbon ratings, and how it manages the conflict between listing and rating.
Whether Xpansiv will go into power analytics M&A that connects to its APX battery position.
Conclusion
Energy transition and environmental markets are consolidating toward a small number of integrated rails, exactly as financial data did before them, and Xpansiv is further along than anyone else. Verdane’s investment is a bet that the company’s breadth compounds into default infrastructure, and that the missing pieces can be bought before rivals assemble their own.
The company’s name has always been its strategy.
Last Week on Asymmetrix
Each week, Asymmetrix publishes several research reports covering companies, sectors and deals in the Data & Analytics industry - available to subscribers only.
Below are just some of the reports published in the past week:
Company Analysis - UK-based insurance and sustainability news and data provider;
Sector Analysis - Legal Data and Intelligence Providers Part 2 - Competitive Landscape;
Company Analysis - UK-based retail intelligence provider;
Sector Analysis - Legal Data and Intelligence Providers Part 3 - From Legal to Leg(AI)l – Legal AI Platforms, Copilots and the Data Question.
Asymmetrix stood up our news desk last month with the hiring of Jordan Bintcliffe. To date, Jordan has published 8 exclusive news stories - scoops on deal processes, investments and fundraises in the Data & Analytics market you don’t want to miss.